The 30-year fixed mortgage rate averaged 7.40 percent for the week ending October 8, 2026, per Freddie Mac's Primary Mortgage Market Survey, and at that rate a $350,000 loan works out to about $2,423 a month in principal and interest. That headline number often stops buyers cold, but affordability in Grand Blanc, Fenton, Linden, Columbiaville and Tyrone Township is really a question of what your full payment looks like and which levers you can pull. This guide walks through the payment math at 7.40 percent, what each community's typical price means for your budget, and the down payment and rate tools that stretch your buying power.
What Lenders Actually Check: The 28/36 Rule
Lenders judge affordability with two debt ratios. The front-end ratio keeps your total housing payment (principal, interest, taxes, insurance, plus any HOA dues) around 28 percent of gross monthly income. The back-end ratio adds all of your other monthly debt, car loans, student loans, credit cards, and usually caps around 36 percent, though many programs allow up to 43 percent or higher with strong compensating factors. On a gross income of $10,000 a month, the 28 percent guideline points to a housing budget near $2,800 a month, which lands most buyers in the roughly $350,000 to $400,000 range depending on local taxes and insurance. Your own numbers depend on income, debt, credit score, and the exact loan program, so treat any guideline as a starting point, not a quote.
What Your Payment Looks Like at 7.40 Percent
The table below shows principal and interest at 7.40 percent with 20 percent down. Taxes, insurance, and any HOA fees are added on top, and your actual rate depends on credit, loan program, down payment, and lock timing.
| Purchase Price | 20% Down Loan | Monthly Principal & Interest |
|---|---|---|
| $250,000 | $200,000 | about $1,385 |
| $300,000 | $240,000 | about $1,662 |
| $350,000 | $280,000 | about $1,939 |
| $400,000 | $320,000 | about $2,216 |
| $450,000 | $360,000 | about $2,493 |
| $500,000 | $400,000 | about $2,770 |
Planning numbers based on a 30-year fixed rate of 7.40 percent with 20 percent down. Principal and interest only; property taxes, homeowners insurance, and any HOA dues are additional. Actual terms vary by lender and borrower.
What That Buys in Each Community
Prices vary widely across the five communities, and so does the monthly payment attached to a typical home. Here is the payment picture at a typical price point in each market, using 20 percent down at 7.40 percent.
- Columbiaville (ZIP 48421): the most affordable entry point, with a Zillow average home value near $264,963, up about 6.6 percent year over year. A home at that value works out to about a $212,000 loan and roughly $1,468 a month in principal and interest. The mix runs from older village homes to cottages near Barnes, McKeen, Miller and Long lakes, and homes here spend longer on market, near 80 days, which gives buyers room to inspect, negotiate, and get a handle on well, septic, and winter systems.
- Grand Blanc: the region's best balance of supply and price. Movoto's September snapshot puts the median list near $324,900, up about 8 percent year over year, with Redfin's median sale near $301,000. At about $325,000, the loan lands near $260,000 and principal and interest near $1,800 a month, with roughly 330 active listings in the market to choose from.
- Linden: a slightly higher price tag for the village feel and lake-country setting. Zillow's average home value sits near $344,000, up about 6.3 percent year over year, and Redfin's three-month median sale runs near $320,000. At about $344,000, expect a $275,000 loan and roughly $1,904 a month in principal and interest, with supply on the thinner side and homes often under contract in 25 to 30 days.
- Fenton: the premium resale market of the group. Movoto lists a median near $397,000 with roughly 250 active homes, while Zillow's average home value holds near $366,570, up about 3.8 percent year over year. At about $397,000, the payment runs to a $318,000 loan and roughly $2,202 a month in principal and interest, and well-priced homes in the competitive 48430 ZIP still go pending in about nine days.
- Tyrone Township: the fastest-moving rural market, with a census-based median home value near $418,300. A home at that value carries about a $335,000 loan and roughly $2,320 a month in principal and interest, and homes in the surrounding Fenton market typically go pending in eight or nine days. For new construction, Oaks of Tyrone by Big Sky Development offers custom homesites from about $629,900, which at 20 percent down lands near $3,490 a month in principal and interest.
The Tax and Insurance Reality in Michigan
Michigan ranks among the higher property-tax states, with an average effective rate around 1.2 percent of home value. SmartAsset puts Genesee County near 1.28 percent, which on a $350,000 home is about $4,500 a year, or roughly $375 a month. Livingston County, which includes Fenton and Tyrone Township, runs lower at roughly 1 percent, about $3,400 a year or $283 a month on the same price. Homeowners insurance adds roughly $100 to $200 a month depending on the home, age, and coverage. One Michigan-specific note: under Proposal A, taxable value grows slowly for long-time owners, but a newly purchased home is taxed on its full value, so budget at the purchase price, not the seller's current bill. Our property tax guide and homeowners insurance guide cover both in detail.
Five Levers That Stretch Your Budget
A 7.40 percent rate does not have to be the final word on your budget. These five levers regularly move the monthly number for buyers across Genesee, Livingston and Lapeer counties.
- Down payment assistance. MSHDA's MI Home Loan pairs with the MI 10K DPA loan, which offers up to $10,000 toward down payment and closing costs as an interest-free loan with no monthly payment, repaid when you sell, refinance, or pay off the first mortgage. The program requires a 640 minimum credit score, homebuyer education, and owner occupancy, and the statewide sales price limit is $566,355 effective June 1, 2026. Income limits vary by county: Lapeer County, which includes Columbiaville, is entirely targeted at $125,760 for a one- to two-person household and $146,720 for three or more, while Genesee's targeted areas run $118,080 and $137,760. Our down payment assistance guide has the full picture.
- Low-down-payment loans. A 3 percent conventional loan and a 3.5 percent FHA loan both cut the cash needed at closing. FHA adds an upfront premium of 1.75 percent plus an annual premium around 0.55 percent, roughly $137 to $138 a month on a $300,000 loan, while conventional PMI typically runs about half a percent to a percent of the loan balance a year. Eligible veterans can use a 0 percent down VA loan, and USDA financing can cover eligible rural areas.
- Seller concessions. In Michigan, buyers can negotiate up to 3 percent seller-paid costs on a conventional loan and 6 percent on FHA, which can cover closing costs or buy down the rate. In a market with seasonal inventory and realistic pricing, concessions are a common part of the negotiation.
- Rate buydowns. A 2-1 buydown lowers the payment for the first two years while income catches up, and paying points at closing lowers the payment for the life of the loan. Both can be written into an offer as a seller concession.
- Let the community do the work. The same monthly payment reaches a higher-priced home in Grand Blanc or Columbiaville than in Fenton or Tyrone Township. If the payment feels tight, compare communities against your budget before you rule out the search.
How Much a Small Change Matters
At 7.40 percent with 20 percent down, every $10,000 of purchase price changes the payment by about $69 a month, and every quarter point of rate changes a $300,000 loan by roughly $45 to $50 a month. That is why locking matters: a rate that drifts from 7.40 to 7.65 percent adds about $50 a month on a $300,000 loan, while negotiating $20,000 off the price saves about $138 a month. None of these are huge on their own, but combined, a seller concession, a buydown, and the right price point can trim several hundred dollars off a monthly payment.
What to Do This Week
Three steps set an October buyer up for success. First, get a full pre-approval so you can lock the moment the numbers work, and have your income and asset documents ready. Second, run the payment math with taxes and insurance for your target community, not just the headline price. Third, tour with an agent who knows street-level conditions in each market. The pre-holiday closing window is tightening, so buyers who want a 2026 closing should move within the next couple of weeks. Our winning offer guide and Thanksgiving calendar cover what comes next.
Ready to see what your payment can buy?
Call Rob Moen directly at (810) 691-0019 for a no-obligation conversation about current listings, rate options, and what your budget reaches across Grand Blanc, Fenton, Linden, Columbiaville and Tyrone Township. We will run the numbers with you and compare communities so you know exactly what a 7.40 percent market means for your next move.
Explore Featured Homes and Listings
To see what is currently available across Grand Blanc, Fenton, Linden, Columbiaville and Tyrone Township, visit our featured homes page for a curated selection of active listings in each community.
Why Work with Rob Moen and The Moen Group?
With more than three decades of experience and thousands of transactions across Genesee, Livingston and Lapeer counties, Rob Moen brings deep market knowledge and sharp negotiation to every client. As Principal Broker of Keller Williams First and a past President of the East Central Association of Realtors, he helps buyers compare communities, structure offers, and act with confidence in every rate environment.
Ready to find your home this fall? Contact Rob Moen at (810) 691-0019 or send a message online. Your next home is waiting.
The Moen Group, Inc. is committed to the Code of Ethics and the principles of fair housing and equal opportunity. All properties and neighborhoods described in this article are available for sale or rent to all persons regardless of race, color, religion, sex, handicap, familial status, national origin, or any other protected class. We encourage and support equal opportunity in housing.
Related Resources
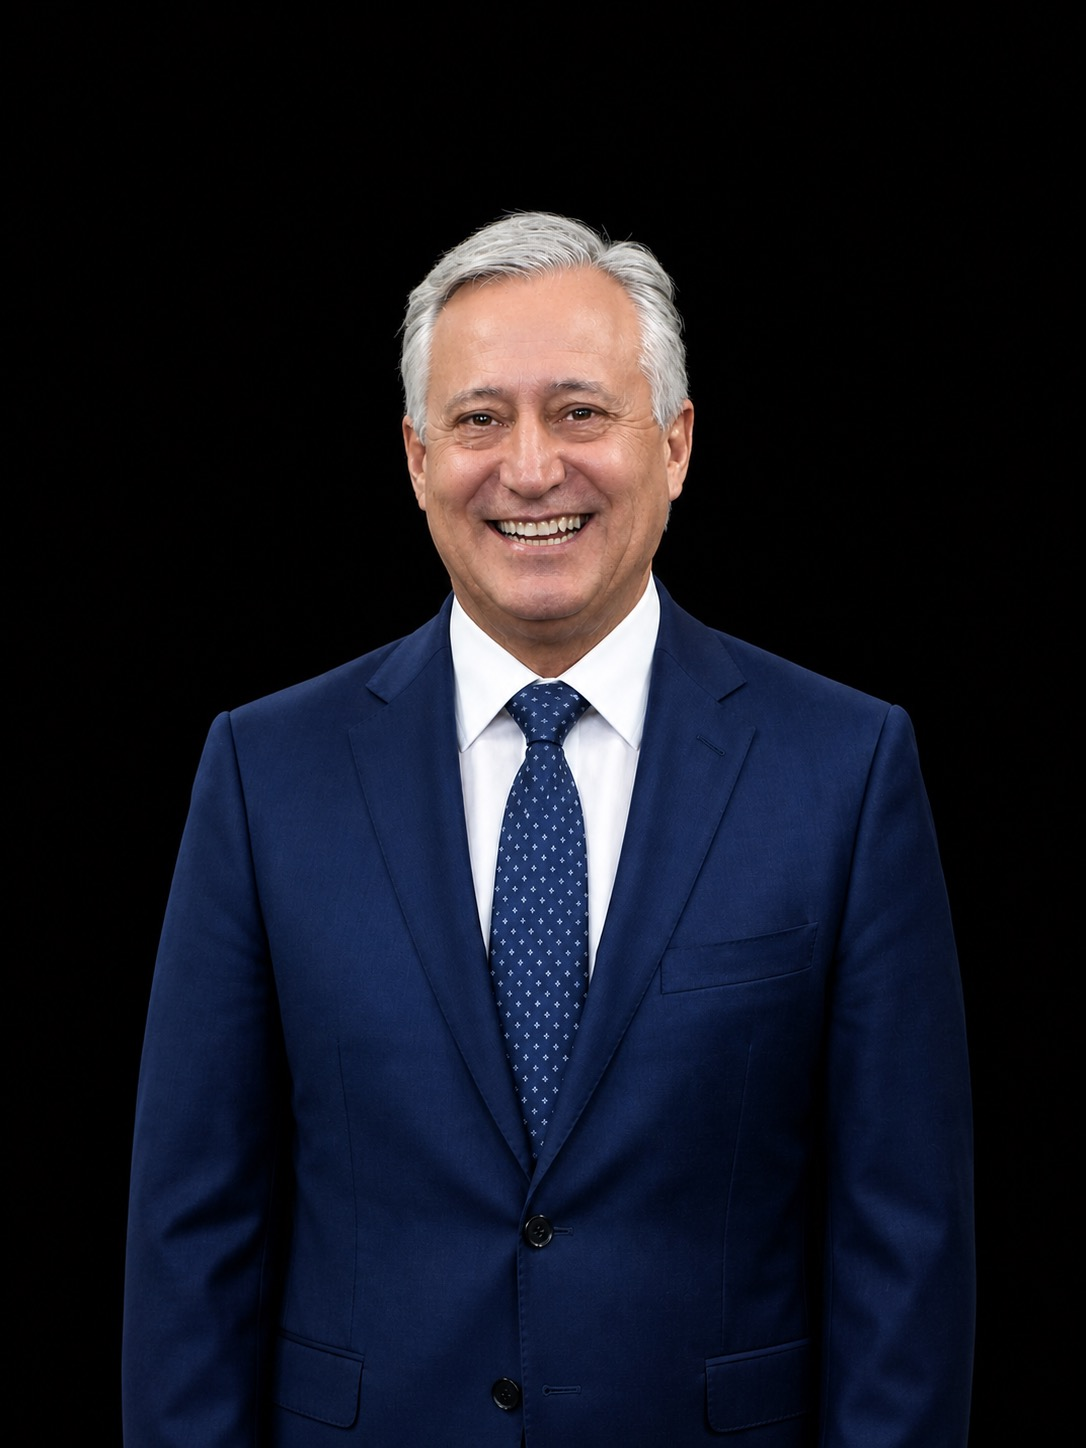
Rob Moen
With more than three decades of experience and thousands of successful home sales across Genesee, Livingston and Lapeer counties, Principal Broker Rob Moen brings deep market knowledge, sharp negotiation skills, and a hands-on approach to every transaction. As a past President of the East Central Association of Realtors and the Women's Council of REALTORS, Rob is committed to helping buyers and sellers in Grand Blanc, Fenton, Linden, Columbiaville, Tyrone Township, Davison and surrounding communities achieve outstanding results.